Real-world asset (RWA) tokenisation is no
longer a conceptual framework. For asset owners and issuers, it has become a
practical question of structure, governance, and regulatory recognition, one
increasingly addressed at the board and shareholder level rather than in
innovation labs.
Nowhere is this shift more visible than in
the UAE, where regulatory regimes (rules and frameworks for overseeing
financial activities), market infrastructure (the systems that enable trading
and settlement of financial assets), and institutional capital (large-scale
investment from organisations such as funds or banks) have converged to make
asset digitisation executable rather than experimental.
As a result, RWA tokenisation is being
evaluated not as a technology initiative, but as a capital-markets and
asset-structuring exercise.
The Mandate: From Feasibility to an
Execution-Ready Tokenisation Blueprint
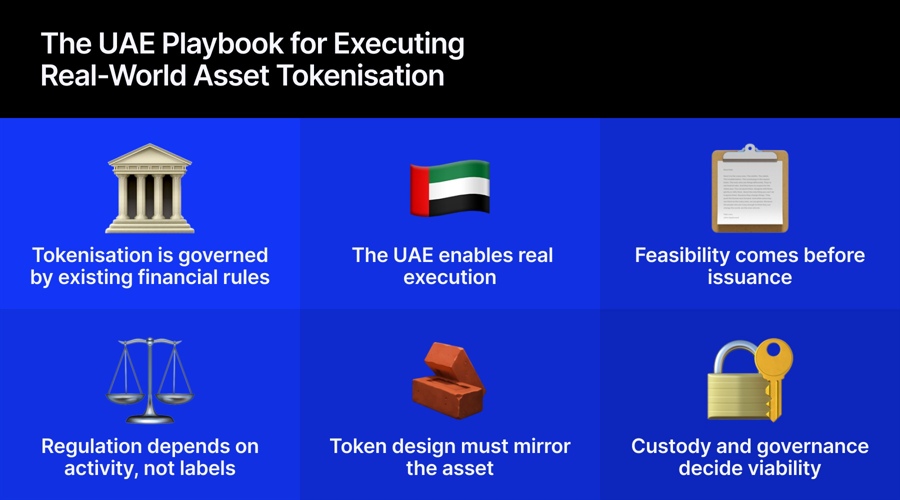
At the institutional level, tokenisation
does not begin with token design. It begins with feasibility, specifically,
whether a tokenised structure can be built that is legally enforceable,
licensed by a reputable regulator, and, most importantly, commercially viable
over time.
In practice, feasibility rapidly expands
into the design of a full tokenisation blueprint. This includes defining the
program’s scope, the token’s lifecycle, the relationship between the underlying
asset and the token’s economics, and the operational dependencies required to
support issuance, holding, and potential secondary activity.
For boards and senior management,
tokenisation is credible only when presented as a complete system. Isolated
token issuance, without clarity on custody, governance, audit, and regulatory
positioning, would not survive institutional scrutiny. The shift from
feasibility to blueprint is therefore the first important step.
🇦🇪🇶🇦HUGE: After UAE, Qatar Financial Centre to kick off real estate tokenization, starting with over $500M worth of towers.
Also in the pipeline: tokenized investment funds and a fresh digital asset regulatory framework.
Dubai picked XRP Ledger for real estate tokenization as… pic.twitter.com/ajlGvWyW1s
— Stellar Rippler🚀 (@StellarNews007) May 25, 2025
Asset Classification in the UAE: How
Regulators Actually Assess RWA Tokens
One of the most critical and most
frequently misunderstood elements of RWA tokenisation in the UAE is regulatory
classification.
The UAE applies an activity-based
regulatory approach, meaning that regulation depends on the specific financial
activities involved rather than the product label. Regulators focus on what a
token represents economically, the rights and obligations it creates, and the
activities surrounding its issuance and distribution. Labels such as
“utility token” or “security token” are secondary, and are
not even present in the regulations.
In practice, this means that asset-backed
tokens may or may not trigger regulated financial activity, depending on the
jurisdiction of the issuance. This assessment has material consequences
for licensing requirements, disclosure obligations, custody rules, and investor
access.
Engagement commonly spans multiple
authorities, including the Dubai Virtual Assets Regulatory Authority, the Abu
Dhabi Global Market, and relevant federal regulators such as the Capital
Markets Authority (CMA) and even the UAE Central Bank. Selecting the
appropriate regulatory perimeter is therefore one of the most important
structuring decisions.
Token Design Must Follow Asset Economics
A recurring lesson in execution is that
token design cannot get abstracted from the underlying asset.
Physical commodities, income-producing
assets, and infrastructure projects each exhibit different economic
characteristics, yield profiles, liquidity constraints, operational risks, and
custody requirements. These characteristics dictate how value can be
represented digitally and what claims tokenholders can reasonably expect.
In practice, this requires mapping asset
economics into enforceable tokenholder rights, issuer obligations, and risk
allocation mechanisms. Yield-bearing structures, for example, must clearly
articulate the source of yield, payment mechanics, and conditions under which
returns may be suspended or adjusted.
Tokens designed independently of asset
realities may function technically, but they tend to collapse under regulatory,
auditor, or investor review. Institutional-grade RWA tokenisation succeeds when
the token is a faithful economic representation of the asset, not a financial
abstraction layered on top of it.
Custody and Bankruptcy Remoteness: The
Institutional Gatekeepers
Custody architecture is often the single
most decisive factor in whether an RWA tokenisation project progresses.
Regulators, auditors, and institutional
investors focus first on asset control: who holds legal title, how assets are
safeguarded, and whether they are insulated from issuer insolvency. These
questions are not theoretical; they determine whether a tokenised structure is
considered credible.
In practice, this usually involves
third-party custodianship, clear asset segregation, and bankruptcy-remote
arrangements that correspond to off-chain legal title with on-chain
representation.
Without this alignment, tokenised assets
struggle to meet institutional acceptance thresholds, regardless of the quality
of the technology stack.
Audit, Verification, and
Proof-of-Reserves
Institutional RWA tokenisation requires
continuous credibility rather than one-time assurances.
Independent audit and verification frameworks, therefore, become foundational.
These may include proof-of-reserves mechanisms, reconciliation between on-chain
records and off-chain custody, and periodic reporting aligned with regulatory
and investor expectations.
In practice, auditors often become de facto
stakeholders in the design of tokenisation. Their ability to verify asset
existence, control, and flows directly influences the regulator’s confidence
and investors’ trust. Projects that defer audit considerations until late in
the process frequently face costly redesigns.
Governance On-Chain and Off-Chain
Tokenisation materially raises governance
standards. Institutional RWA structures require clearly defined issuer
obligations, tokenholder rights, operational controls, and escalation
mechanisms. These governance models must operate coherently across smart
contracts and traditional legal documentation.
Boards and regulators pay particular
attention to accountability: who can make changes, under what conditions, and
how those changes are communicated. Governance design is therefore not an
accessory to tokenisation—it is central to approval and sustained viability.
Read more: SEC Clarifies the Rules Around Tokenised Stocks – Will It Encourage US Issuers Now?
Legal Architecture and Cross-Border
Structuring
Institutional RWA tokenisation in the UAE
is rarely confined to a single jurisdiction.
Legal architecture must address
enforceability, liability allocation, disclosure obligations, and cross-border
regulatory interactions.
Given the issuer’s international footprint,
a comparative analysis was also conducted across the UAE, Switzerland, and the
EU under the Markets in Crypto-Assets Regulation (MiCA), a European Union legal
framework for crypto-asset markets. While MiCA provides standardisation and
clarity, it also introduces heavier disclosure and liability regimes.
Switzerland offers alternative structuring options, each with its own
trade-offs.
In many institutional cases, hybrid
structures emerge as the most pragmatic solution. The UAE frequently serves as
the anchor jurisdiction due to its flexibility and regulator engagement model,
while other jurisdictions are integrated where appropriate.
Commercial Execution and Board-Level
Decision Frameworks
Regulatory compliance, though essential, is
only one component of a viable RWA tokenisation program. In practice, many
technically compliant projects still fail to progress because commercial
execution has not been adequately designed or stress-tested.
At the institutional level, tokenisation
delivers a new operational and economic model that must function coherently
across issuance, holding, servicing, and—where applicable—secondary activity.
This requires clearly defined token issuance flows, lifecycle mechanics, and
risk apportionment across all participating parties, including the issuer,
asset custodian, auditor, technology providers, and any distribution or trading
venues.
From an execution standpoint, one of the
most critical deliverables is translating these design choices into board-level
briefing materials and decision frameworks. Senior stakeholders are not
evaluating tokenisation on novelty; they are assessing downside risk, capital
efficiency, reputational exposure, regulatory durability, as well as strategic
optionality. They expect to understand how the structure behaves under stress
scenarios, how liabilities are allocated, and what operational dependencies
exist over the life of the program.
Projects that reach execution successfully
tend to share a common characteristic: tokenisation is treated as a coordinated
commercial program from the outset, with defined ownership, governance, and
accountability. By contrast, initiatives that approach tokenisation primarily
as a compliance exercise commonly struggle to secure final approvals, as
commercial and operational questions surface too late in the process.
The Core Lesson for Asset Owners and
Issuers
Once tokenisation moves from concept into execution, a consistent lesson emerges: RWA tokenisation is not a single discipline, nor can it be delivered by any one function in isolation. Successful institutional tokenisation requires integrating multiple domains – asset
economics, regulatory classification, legal structuring, custody design, audit
and verification, governance, and ongoing operational execution. Weakness or
ambiguity in any one of these areas tends to undermine confidence in the entire
structure.
For asset owners, this frequently
represents a cultural shift. Tokenisation exposes assumptions that may have
been implicit in traditional asset structures, forcing explicit decisions
around control, transparency, and accountability. It also demands closer
coordination between legal, finance, operations, and technology teams than many
organisations are accustomed to.
Where these elements are aligned into a
single, logical framework, tokenisation becomes a durable institutional
solution, capable of sustaining long-term capital strategies and regulatory
engagement. Where they are not, tokenisation remains an experimental
initiative, vulnerable to regulatory pushback, investor scepticism, or
operational friction.
Complexity Is a Challenge
The UAE has positioned itself as one of the
most credible and commercially viable environments globally for institutional
RWA tokenisation. Its regulatory posture, market infrastructure, and engagement
model provide asset owners with a framework for assessing and implementing
tokenisation with a high degree of confidence.
That said, the UAE’s advantages do not
eliminate complexity. They reward asset owners and issuers who approach
tokenisation as a structural, regulatory, and governance challenge rather than
a technology launch or branding exercise.
In institutional RWA tokenisation, the
difference between concept and execution is not incremental. It is decisive.
Real value is created not at the point of issuance, but in the quality of the
framework that supports the asset over its lifecycle.